

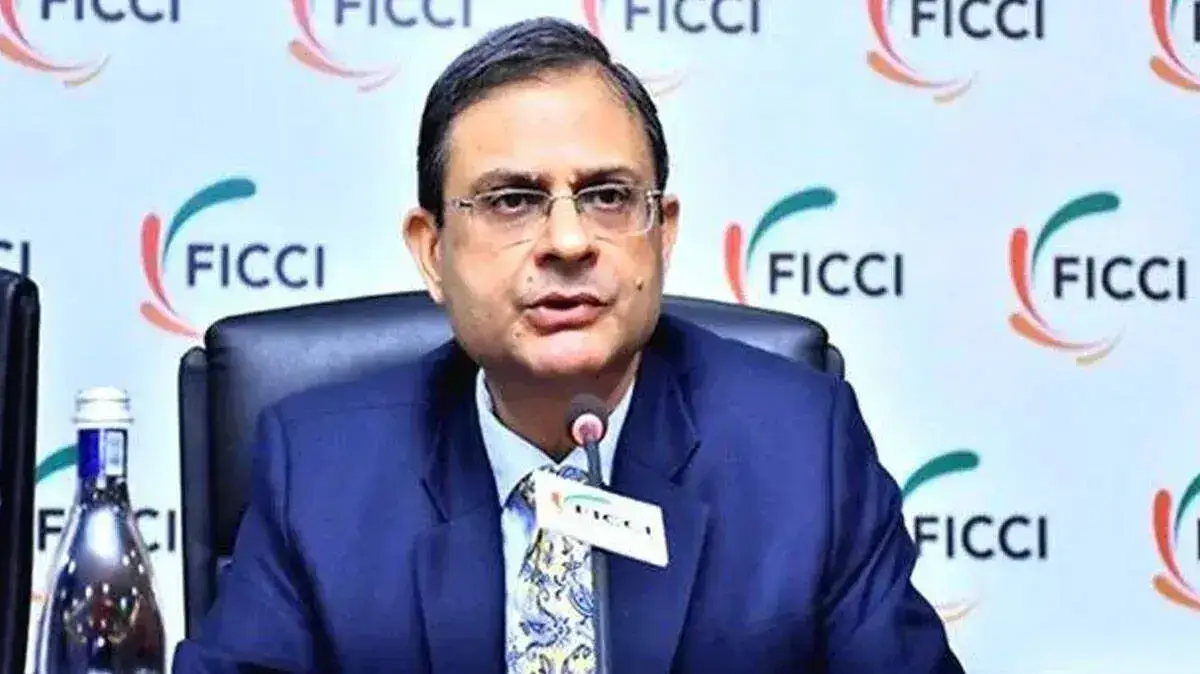
NEW DELHI: The Reserve Bank of India (RBI) has raised the benchmark interest rate as it announced its monetary policy for the first time in three-and-a-half years. The repo rate was increased by 0.25 percentage points to 5.50%. This is expected to pave the way for an increase in interest rates on home, vehicle and personal loans. RBI Governor Sanjay Malhotra announced the policy decision. The announcement came as the three-day meeting of the Monetary Policy Committee was scheduled to conclude today.
Bank lending rates are also expected to rise in proportion to the repo rate hike. However, the increase will not affect all types of loans. It will primarily impact repo-linked loans, floating-rate loans and new loans. Loans with fixed interest rates will not be affected by the rate hike. Meantime, the increase is good news for those who have bank fixed deposits (FDs) as well as those planning to open new FDs. Banks are expected to offer a slight increase in FD interest rates, which would benefit depositors.
The RBI had cut interest rates by a total of 125 basis points in 2025, following which it had kept the policy rate unchanged for four consecutive meetings. However, inflationary pressures and rising crude oil prices are believed to have prompted the central bank to reconsider its stance. At the same time, global uncertainties are also understood to have encouraged the RBI to adopt a more cautious approach to monetary policy.



 HOME
 LATEST
 NOTIFIED NEWS
 POLL
 KERALA
 EDITORIAL
 INDIA
 WORLD
 BUSINESS
 CINEMA
 SPORTS
 LIFESTYLE
 SPECIAL
 SCIENCE & TECHNOLOGY

 |